Ghana's 2026 IMF Exit and the Road Beyond Aid
How Ghana slid from a 'Ghana Beyond Aid' dream into default, restructured its debt without cash, and is now trying to make its seventeenth IMF programme the last.
By Eddie Forson · 28 August 2026 · 13 min read
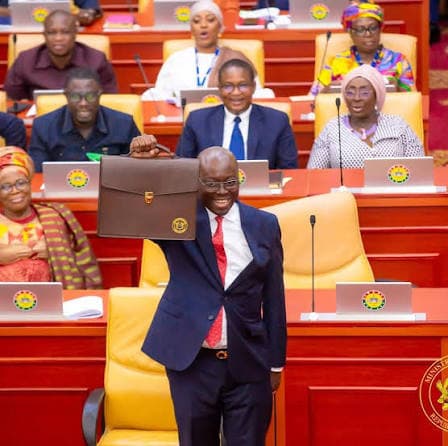
Ghana's relationship with the International Monetary Fund reads like a pendulum. It swings toward reform, discipline and self-sufficiency, then swings back toward crisis, downgrade and rescue. Since independence, the country has entered IMF programmes more than a dozen times. Each exit has been announced as the last. Each return has been framed as an unfortunate accident of external shocks.
The most recent arc is the most instructive. In 2019, Ghana walked away from a four-year IMF arrangement with single-digit inflation, a cleaned-up banking sector and a governing slogan — "Ghana Beyond Aid" — that promised the country would never again queue at the Fund's door. Barely three years later, in December 2022, Ghana defaulted on most of its external debt and went back to Washington for a fresh rescue.
Understanding how that happened — and whether the exit now underway can hold — matters enormously for the millions of Ghanaians abroad who send money home and for the foreign investors weighing whether Accra is a durable bet. This analysis traces the full cycle: the shadowed success of the 2015–2019 programme, the 2022 fiscal cliff, the mechanics of re-entry and default, the debt restructuring that substituted for cash repayment, the legal frameworks that failed, and the growth-versus-austerity tightrope that Ghana's economic managers must now walk.
Introduction: The Pendulum of Ghana's Economic Sovereignty
Ghana's economic sovereignty has always been conditional. The country is rich in gold, cocoa and, since 2010, oil — yet it has repeatedly found itself dependent on external financing to bridge the gap between what the state spends and what it collects.
The pattern is structural rather than accidental. Revenue mobilisation has chronically lagged spending commitments, especially around election years, when incumbent governments have historically loosened the purse strings. The result is a recurring boom-bust rhythm: expansion, deficit, currency pressure, downgrade, and eventually an IMF programme to restore order.
The 2015–2019 and 2023 programmes are two halves of the same story. To see why the exit now in progress could be different, you first have to see clearly how the last one collapsed.
Ghana has entered IMF arrangements numerous times since independence. The programme approved in 2023 is widely counted as the country's seventeenth. Breaking that cycle — not merely completing another review — is the real test.
The Legacy of the 2015 ECF: Exit Under Shadowed Success
The Extended Credit Facility that anchored Ghana's finances from 2015 to 2019 was initiated under President John Mahama's administration, which turned to the Fund after a currency and fiscal crisis. According to the IMF's own record of the programme, it was a roughly US$918 million arrangement designed to restore debt sustainability and macroeconomic stability.
The programme ran through Ghana's 2016 election and the subsequent transition to President Nana Akufo-Addo's government, which inherited it and carried it to completion. The IMF's Press Release 19/84, dated March 20, 2019, records the final disbursement under the arrangement of SDR 132.84 million, approximately US$185.2 million. By the IMF's account, Ghana met the programme's core conditions: it achieved its end-2018 fiscal targets, submitted a Tax Exemption Bill to Parliament, executed a comprehensive banking-sector clean-up that recapitalised or wound down insolvent lenders, and maintained single-digit inflation alongside primary fiscal surpluses.
On paper, this was a success. The Akufo-Addo administration used the moment to declare a new era. "Ghana Beyond Aid" became the organising ambition of national economic policy — a promise that the country would fund its own development and never again submit to Fund conditionality.
The 2019 exit was real but fragile. The banking clean-up left the state with large recapitalisation costs, and the fiscal surpluses depended on discipline that election-year politics would soon test. Exiting a programme is not the same as curing the disease that made the programme necessary.
The 2022 Fiscal Cliff: How the Gaps Reopened
The relapse came fast. Three forces converged.
First, COVID-19. The Ghana Investment Promotion Centre's Third Quarter 2021 report noted that the pandemic continued to depress the global drivers of growth, especially foreign direct investment, and that a substantial recovery of FDI in Africa was unlikely given the continent's structural weaknesses, lack of fiscal space and dependence on greenfield investments. Ghana's government responded to the pandemic, as most did, with emergency spending and revenue losses — and it suspended the fiscal rule that was supposed to cap the deficit.
Second, the Russia-Ukraine shock of 2022 drove up global food and energy prices, widening Ghana's import bill and draining foreign reserves precisely when the country needed them most.
Third, and most damaging, the pre-existing structural weaknesses. High debt, a thin revenue base and a heavy interest bill left no cushion. When markets took fright, there was nothing to fall back on.
The GIPC's Q3 2022 Quarterly Investment Report captured the mood from inside Ghana's investment-promotion machinery: the CEO wrote that post-pandemic FDI inflows remained fragile, marked by significant investment uncertainty and the deferral of both greenfield and brownfield projects, and openly pinned hopes for stabilisation on the ongoing negotiations with the IMF.
The 2022 crisis was felt most acutely in the exchange rate. Remittances that once converted into a stable number of cedis suddenly bought far more, but the families receiving them faced runaway inflation that ate the difference. Currency collapse is never a windfall when prices are chasing it upward.
The Mechanics of Re-entry: From Market Rejection to the 2023 ECF
Losing access to capital markets is a process, not an event, and the credit-rating agencies documented every step.
According to Fitch Ratings, Ghana was downgraded from B to B- with a negative outlook on January 14, 2022, citing a surge in debt and a high interest-to-revenue ratio. According to Moody's Investors Service, Ghana was cut from B3 to Caa1 on February 4, 2022, on weak revenue generation and liquidity challenges. The decisive blow came in August 2022: S&P Global Ratings lowered Ghana to CCC+, and Fitch Ratings followed by dropping the rating to CCC. At that point, the door to affordable international borrowing was shut.
Once a government cannot roll over its debt in the market, it has only two options: print money and watch the currency collapse, or seek an official rescue. The Akufo-Addo administration chose the second. On December 19, 2022, the government formally announced a suspension of payments on most external debt, including Eurobonds and commercial loans — a selective default, confirmed in the record of both Fitch Ratings and the IMF.
That default was the price of admission for a new programme. In 2023, Ghana secured a roughly US$3 billion Extended Credit Facility. The "begging," to use the brief's blunt word, was really a negotiation: the IMF would not lend into an unsustainable debt situation, so Ghana had to demonstrate that its creditors — foreign and domestic — would share the pain first.
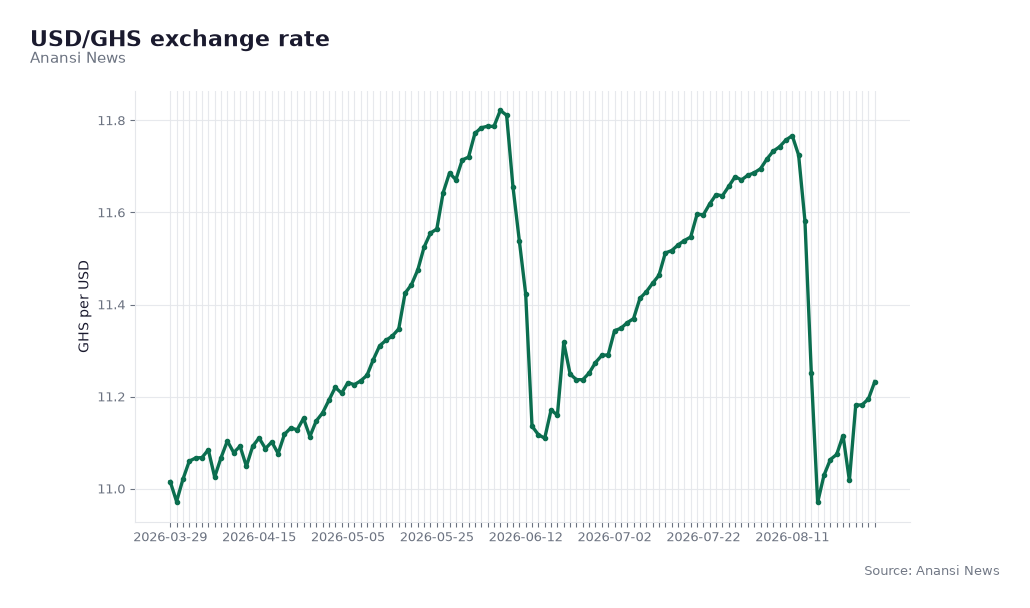
The cedi's path against the US dollar frames the stakes of every fiscal decision Ghana's managers make. Source: Anansi News.
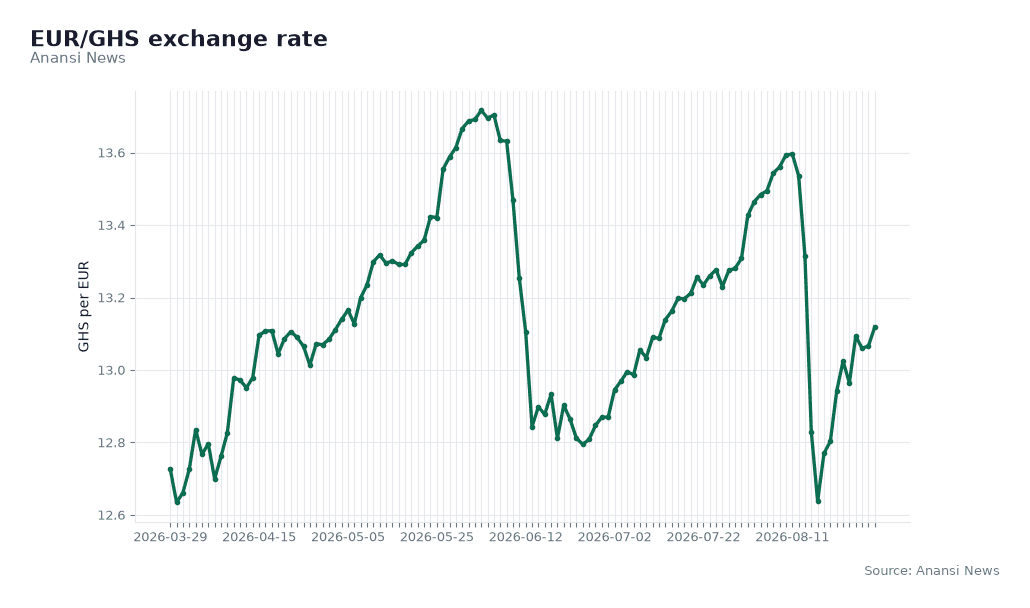
The scale of the currency stress is visible in the numbers that markets still watch. As of late August 2026, the USD/GHS rate stood at 11.23, against a prior reading of 11.20, a change of +0.3%. The euro was quoted at 13.12 cedis, from a prior 13.07, a move of +0.4%. These figures, drawn from market data compiled by the Bank of Ghana and wire services, show a currency that — after the violence of 2022 — has settled into comparative calm.
Debt Restructuring: Repaying by Reconfiguring
Here is the crucial point that headlines about "repaying the IMF" tend to obscure: Ghana did not dig up billions of dollars in cash to settle its debts. It reconfigured them.
The centrepiece was the Domestic Debt Exchange Programme, or DDEP, launched by the Akufo-Addo administration in December 2022. According to the Ministry of Finance's DDEP notices and the IMF's programme documentation, the exercise aimed to restructure roughly GH¢137 billion of local debt to make the US$3 billion IMF deal viable.
The design was deliberately unusual. According to the same documentation, there were no nominal haircuts on principal — bondholders were promised 100% of their principal back. The pain came instead through interest and time. Coupons were slashed to 0% in 2023, 5% in 2024, and 10% from 2025 until maturity. Existing bonds were swapped for twelve new instruments with staggered maturities running from 2027 out to 2038.
In plain terms, Ghana "repaid" by paying investors less interest, later. Pensioners, banks and individual bondholders absorbed the cost through years of thinner returns and deferred capital. Alongside the domestic exchange, the government negotiated with external commercial creditors and bilateral lenders to restructure the foreign debt suspended in December 2022.
The table below summarises the mechanics.
| Element | What happened | Source |
|---|---|---|
| 2015–2019 ECF size | ~US$918 million | IMF Press Release 19/84 |
| Final 2019 disbursement | SDR 132.84 million (~US$185.2 million) | IMF Press Release 19/84 |
| External default declared | December 19, 2022 | Fitch Ratings; IMF |
| New 2023 ECF | ~US$3 billion | IMF |
| Domestic debt restructured (DDEP) | ~GH¢137 billion | Ministry of Finance; IMF |
| DDEP principal haircut | None (100% principal preserved) | Ministry of Finance |
| DDEP coupons | 0% (2023), 5% (2024), 10% (from 2025) | Ministry of Finance |
The DDEP set an important precedent — Ghana chose to protect nominal principal and shift the burden onto yield and maturity. That is friendlier to long-term holders than an outright principal write-down, but it also means real returns were compressed for years. Read the coupon schedule, not just the reassuring word "no haircut."
The Fiscal Responsibility Act vs. Economic Reality
Ghana was not without rules. The Fiscal Responsibility Act of 2018 was meant to be the guardrail — a legal cap on the deficit intended to stop exactly the kind of overspending that produced the 2022 crisis.
It failed, for a reason that exposes the weakness of unenforced fiscal law: when COVID-19 struck, the government simply suspended the Act. A rule that can be switched off at the moment of maximum temptation is not much of a rule. The 2018 framework also lacked meaningful sanctions and an independent watchdog with the standing to say no to a spending minister.
The reforms that followed were an attempt to give the framework teeth. According to reporting on the Public Financial Management (Amendment) Act, 2025 (Act 1136), the 2018 Fiscal Responsibility Act was repealed and its rules folded into the broader public financial management framework for stronger enforcement. The new architecture, as described in that legislation, adds an independent Fiscal Council established as a legislated autonomous body; a primary balance rule mandating a minimum annual primary surplus of 1.5% of GDP; a debt ceiling capping debt-to-GDP at 45% by 2034; and — most strikingly — personal liability for officials, including provisions for the imprisonment of ministers who cause significant fiscal slippages.
The difference between the 2018 and 2025 frameworks is the difference between a suggestion and a deterrent. A rule with an independent enforcer and personal criminal liability is far harder to suspend on the eve of an election. Whether Ghana's political class actually submits to it is the open question.
Growth vs. Austerity: The Current Government's Tightrope
The hardest task facing Ghana's economic managers under the Akufo-Addo administration was never simply to cut. It was to cut waste while still investing in growth — because austerity without growth is a recipe for the next crisis.
The IMF-supported strategy, the Post-COVID-19 Programme for Economic Growth (PC-PEG), tried to square that circle: consolidate the budget, protect the vulnerable, and pivot the engine of expansion from public spending toward private investment. On the discipline side, that meant reworking the tax base. The E-Levy on electronic transactions, initially set at 1.5%, was reduced to 1.0% in January 2023 and, according to reporting on subsequent budget measures, ultimately repealed in 2025 by the Mahama administration. The Value Added Tax Act, 2025 (Act 1151), effective January 1, 2026, abolished the 1% COVID-19 Health Recovery Levy and consolidated levies into a unified 15% rate to simplify computation and reduce cascading taxes.
The results were mixed. According to the 2023 tax performance record, revenue exceeded targets in direct taxes such as company and PAYE income tax, but domestic VAT collections came in below target — a reminder that consumption taxes are hard to enforce in a largely informal economy.
On the stabilisation side, the Bank of Ghana leaned on gold. Through its gold-for-oil scheme and foreign-exchange interventions, the central bank sought to steady the cedi after the currency's steep 2022 depreciation. According to figures cited in IMF programme documents, gross international reserves recovered substantially through the programme period. The same documents note that these interventions carried real costs, described as "policy losses" tied to exchange-rate differentials and the expense of incentivising miners to sell gold through official channels.
Gold's role in Ghana's stabilisation makes the metal's global price directly relevant to the country's fortunes. As of late August 2026, gold traded at $4,608 per ounce, down from a prior $4,650, a change of -0.9%, according to market data tracked alongside the Bank of Ghana's reserve reporting. High gold prices flatter Ghana's exports, reserves and current account — but they are set in London and New York, not Accra.
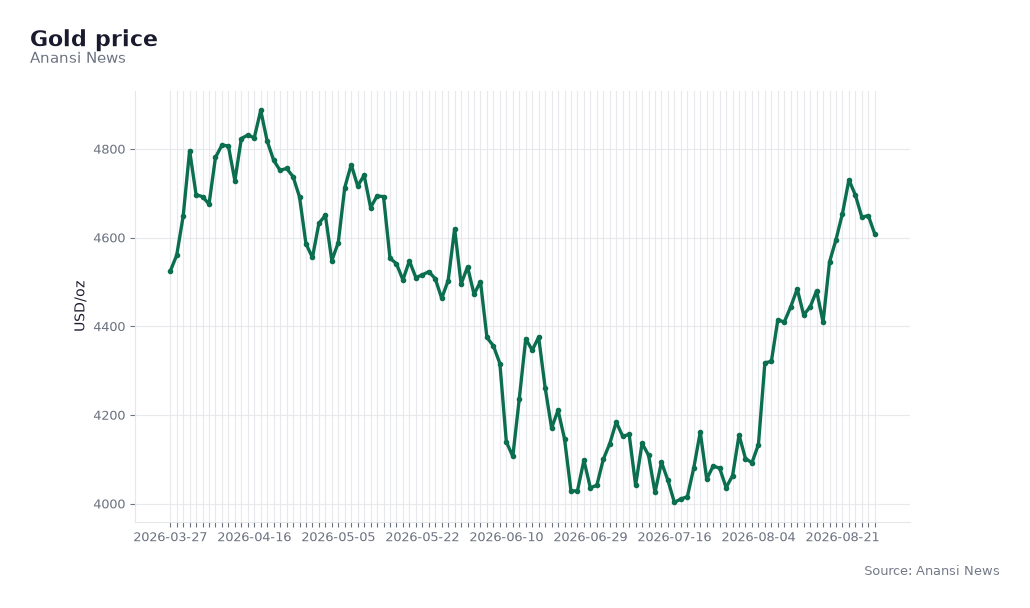
Gold's elevated global price has been a quiet ally of Ghana's reserve rebuild. Source: Anansi News.
Who Sets the Price of Ghana’s Recovery?
The global reference price for gold is struck twice a day, at 10:30 and 15:00 London time. The auction is run by ICE Benchmark Administration for the London Bullion Market Association. Its participants are international bullion banks and trading houses. No Ghanaian institution is among them. Between auctions, the price moves on COMEX futures positioning in New York, on exchange-traded fund flows, on US real interest rates and on the dollar. None of that has anything to do with output at Obuasi or Tarkwa. Ghana was the world's sixth-largest producer in 2025, at 187.3 tonnes against global mine supply of 3,672 tonnes. That is roughly five per cent of the world's gold. Yet it has no seat at the table where it is priced.
Ghana's own institutions now build this in. Since 1 July 2026, the Ghana Gold Board has set its mandatory cedi purchase price by converting the LBMA morning and afternoon benchmarks at the Bank of Ghana reference rate. Gold is bought in Accra, in cedis, from Ghanaian miners, at a number computed in London. This reform is intended to replace discretionary pricing by buyers. But it localises settlement, not price formation.
Price is only half of the challenge though. Acceptance in the wholesale market runs through the LBMA's Good Delivery List. Rand Refinery in South Africa is the only African name on it. None of Ghana's four licensed refineries qualifies. So the metal has left the country as doré, to be refined and assayed elsewhere. The refining margin, the assay fees and the trading spreads are earned abroad. GoldBod's answer took effect on 1 September 2026: no unrefined doré may be exported without proof of domestic refining. Gold Coast Refinery is pursuing accreditation through a partnership with Rand. Until that lands, foreign buyers can still demand a re-assay or a remelt, and the cost comes off the seller's price.
This is not a grievance. It is a balance-sheet problem. According to the Ghana Statistical Service, gold made up 63.1 per cent of exports in 2025, against 38.5 per cent in 2004. Bank of Ghana trade figures put gold at $12.5bn of the record $18.2bn exported in the first half of 2026. Reserves held in the metal are marked to a price set abroad. The buffer that bought Ghana its IMF exit can therefore shrink without a single policy error in Accra. The Fund's own stress tests name a gold price shock among the gravest threats to debt sustainability. The Government Statistician put it plainly: gold is the anchor, and the greatest exposure.
The windfall is not evenly kind at home either. A cedi lifted by gold receipts returns fewer cedis per dollar to cocoa farmers and to non-traditional exporters. Government raised the guaranteed cocoa producer price to GH¢51,660 per tonne for the 2025/26 season, up from GH¢49,600. That is a cushion, not a cure. The same external price that repairs the reserve position squeezes the sectors that would diversify away from it.
Seen this way, the exit is less an escape from external dependence than a change of counterparty. Bondholders and the IMF have given way to a commodity market. The difference matters. A creditor can be negotiated with. A benchmark cannot.
Breaking the 17-Program Cycle: Strategies for Permanent Exit
Completing a programme is easy compared with never needing another one. Ghana has done the former sixteen times. The strategies aimed at making the seventeenth the last fall into three buckets.
The first is revenue mobilisation. The VAT reform of 2025 and the broader effort to widen the tax net are attempts to raise domestic revenue without repeatedly inventing distortionary levies like the E-Levy that governments later feel compelled to repeal. A state that collects enough to fund itself does not need to borrow itself into crisis.
The second is institutional autonomy, above all for the Bank of Ghana. A central bank that can resist pressure to finance the government's deficit — the so-called monetary financing that helped ignite the 2022 inflation — is the single most important firewall against relapse. Alongside it sits the new independent Fiscal Council, intended to give an arms-length body the authority to sound the alarm before spending spins out of control.
The third is the enforcement architecture already described: the primary surplus rule, the 45% debt ceiling by 2034, and the personal liability provisions of Act 1136. Rules that bite change political incentives in a way that slogans never did.
| # | Period | Facility | Agreed (SDR m) | Drawn (SDR m) | Circumstances |
|---|---|---|---|---|---|
| 1 | May 1966 – May 1967 | Standby | 36.4 | 31.4 | Three months after the coup that removed Nkrumah. Empty reserves, heavy short-term supplier credits, collapsed cocoa prices. |
| 2 | May 1967 – May 1968 | Standby | 25.0 | 25.0 | Supported the July 1967 devaluation and a first rescheduling of supplier debts. |
| 3 | May 1968 – May 1969 | Standby | 12.0 | 12.0 | Stabilisation under military rule, ahead of the return to civilian government. |
| 4 | May 1969 – May 1970 | Standby | 5.0 | 5.0 | The smallest on record. Busia's Second Republic took office with reserves still thin. |
| 5 | Jan 1979 – Jan 1980 | Standby | 53.0 | 32.0 | After nine years outside the Fund, with inflation above 70%. The programme lapsed in the upheaval of 1979, and only 60% was drawn. |
| 6 | Aug 1983 – Aug 1984 | Standby | 238.5 | 238.5 | The Economic Recovery Programme. Drought, bushfires, collapsed cocoa output, and roughly a million Ghanaians expelled from Nigeria. |
| 7 | Aug 1984 – Dec 1985 | Standby | 180.0 | 180.0 | Phase two of the ERP: further devaluation, price decontrol, rebuilding cocoa and mining output. |
| 8 | Oct 1986 – Oct 1987 | Standby | 81.8 | 81.8 | Financed the move to a foreign exchange auction, and then to licensed forex bureaux. |
| 9 | Nov 1987 – Nov 1988 | Extended Fund Facility | 245.4 | 97.6 | Cancelled after a year and rolled into the concessional facility below. Hence the partial drawing. |
| 10 | Nov 1987 – Nov 1988 | Structural Adjustment Facility | 129.9 | 40.9 | Ran alongside the EFF on concessional terms, and was superseded with it. |
| 11 | Nov 1988 – Mar 1992 | ESAF | 388.6 | 388.6 | The high tide of adjustment: privatisation, retrenchment, cost recovery. Ghana became the Fund's showcase reformer in Africa. |
| 12 | Jun 1995 – May 1999 | ESAF | 164.4 | 137.0 | Election-year spending after the 1992 return to multiparty rule. Inflation back near 70%. Street protests forced the withdrawal of VAT in 1995. |
| 13 | May 1999 – Nov 2002 | PRGF | 228.8 | 176.2 | Cocoa and gold prices fell as oil rose. The cedi lost roughly half its value in 2000. Ghana opted into HIPC in 2002. |
| 14 | May 2003 – Oct 2006 | PRGF | 184.5 | 184.5 | Carried Ghana to HIPC completion point in July 2004 and into multilateral debt relief. External debt in present-value terms fell to around $2.4bn. |
| 15 | Jul 2009 – Jul 2012 | ECF | 387.5 | 387.5 | A 2008 election-year deficit of roughly 14% of GDP met the global financial crisis. Oil production began in 2010, mid-programme. |
| 16 | Apr 2015 – Mar 2019 | ECF | 664.2 | 664.2 | About $918m. Dumsor, a collapsing cedi, and a wage bill swollen by Single Spine. Begun under one government and completed by its successor. |
| 17 | May 2023 – Jul 2026 | ECF | 2,241.9 | 2,241.9 | About $3bn. External default, the domestic debt exchange, inflation above 50%. The final $371m was released on 27 July 2026. |
History of the 17 IMF crises Ghana suffered so far.
The macro backdrop is helping. Ghana's real GDP growth was recorded at 6.0% in the latest reading, up from 5.8%, an improvement of +0.1 pp, according to the Ghana Statistical Service. The Bank of Ghana's Monetary Policy Report for September 2025 noted that headline inflation had declined for several consecutive months, driven by a tight monetary policy stance, stepped-up liquidity sterilisation, downward revisions in ex-pump petroleum prices and exchange-rate stability. The Bank's external-sector commentary from May 2025 pointed to a record provisional current account surplus in the first quarter of that year, driven mainly by higher prices and increased production volumes of gold and cocoa, together with strong remittance inflows — the very forces that rebuild reserves and reduce the need for external rescue.
Watch whether the Fiscal Council is genuinely allowed to operate independently, whether the primary-surplus rule survives the next election cycle intact, and whether domestic VAT collections finally close the gap with target. Those three signals will tell you more about permanent exit than any headline growth number.
Conclusion: A Hopeful Horizon for Investors and Diaspora
Ghana's story is not one of a country that cannot reform. It is one of a country that reforms and then relapses — that exits the IMF and then walks back in. The question is never whether Ghana can stabilise; the 2015–2019 programme proved it can. The question is whether it can stay stable when the political calendar tempts it otherwise.
There are genuine reasons for hope. The macro picture has brightened: growth has firmed, inflation has fallen, the current account has swung to surplus on the strength of gold, cocoa and remittances, and the cedi has held far steadier than it did in the chaos of 2022. Crucially, the reforms this time reach beyond numbers to institutions — an independent Fiscal Council, a strengthened public financial management law with real sanctions, and a debt ceiling with a date attached.
For the diaspora, that combination of falling inflation and a steadier currency means remittances stretch further and mean more to the families who receive them. For foreign investors, the improved transparency and the credible-until-proven-otherwise fiscal framework make Ghana a more legible long-term destination for capital than it was during the market rout of 2022.
None of this guarantees that the seventeenth programme will be the last. But for the first time in this cycle, the tools to break the pendulum's swing are written into law rather than into a slogan. That, more than any single quarter's data, is what makes the horizon a hopeful one.
Sources: Anansi market data, Bank of Ghana, Ghana Investment Promotion Centre.
Cite us / embed this
Reusing a chart or stat? Please credit Anansi News and link back to this page.
Sources: Anansi market data, Bank of Ghana, Ghana Investment Promotion Centre.
Charts
Sources
- 1.ghanaweb.com
- 2.fitchratings.com
- 3.spglobal.com
- 4.imf.org
- 5.mofep.gov.gh
- 6.ey.com
- 7.Bank of Ghana. September 17, 2025 (p. pp.1-2)
- 8.Bank of Ghana. May 28, 2025 (p. pp.4-6)
- 9.Ghana Investment Promotion Centre. Q3-2022-Quarterly-Investment-Report.pdf (p. pp.1-3)
- 10.Ghana Investment Promotion Centre. Q3-2022-Quarterly-Investment-Report.pdf (p. p.1)
- 11.Bank of Ghana. July 25, 2025 (p. pp.54-56)
- 12.Bank of Ghana. Monetary Policy Report September 2025 (p. pp.5-6)
- 13.Ghana Investment Promotion Centre. Third-Quarter-2021-GIPC-Investment-Report-01112021-1.pdf (p. p.1)
- 14.Bank of Ghana. Monetary Policy Report July 2026 (p. pp.6-7)
- 15.Anansi market data. Gold price
- 16.Anansi market data. EUR/GHS exchange rate
- 17.Anansi market data. GDP growth (Ghana)
- 18.Anansi market data. USD/GHS exchange rate
Related: John Mahama News